You've found a payment provider that accepts your pharmacy or supplement shop. Then you read the contract and see it: "rolling reserve: 10% for 180 days."
It sounds like they're keeping your money. In a way, they are, but only temporarily. Here's how reserves work, why you're being asked for one, and how to get better terms.
What is a rolling reserve?
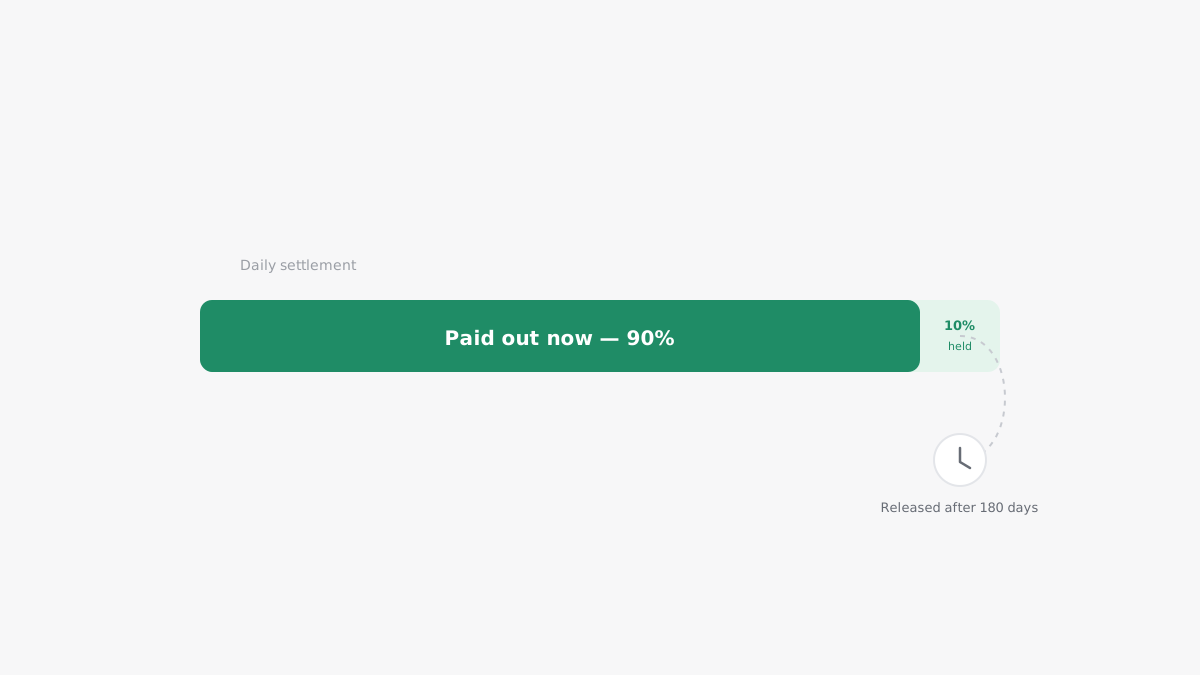
A rolling reserve is a safety buffer. Your payment provider keeps back a small percentage of each day's sales for a set period, then releases it to you.
A simple example:
- You sell €1,000 on 1 March
- The reserve is 10% for 180 days
- You receive €900 straight away (minus normal fees)
- The other €100 is released to you about 180 days later, in late August
The "rolling" part means this happens every day. After the first few months, money is being released to you every day as well as held back, so it becomes a steady cycle rather than a growing pile.
Why do providers ask for a reserve?
When a customer disputes a card payment, the money goes back to the customer, and the payment provider has to cover it first. If your business closed or couldn't pay, the provider would lose that money.
Health, pharmacy and supplement businesses are seen as higher risk because of:
- Disputes that arrive months later. Customers can often dispute a card payment many weeks after the purchase.
- Subscriptions, where forgotten repeat charges lead to disputes
- Regulatory changes that could affect your products overnight
- Industry history. A few bad actors make everyone in the category look riskier.
The reserve means the provider has something to fall back on. For you, it's often the price of getting approved at all.
What's typical?
Terms vary a lot by provider and business, but commonly:
- Percentage: often around 5% to 10% of sales
- Holding period: often 90 to 180 days
New businesses, businesses with no processing history, and those in categories like CBD or subscriptions usually start at the higher end.
Other types of reserve you may see
- Upfront (capped) reserve: a fixed amount held at the start, instead of a percentage of each sale
- Capped rolling reserve: a percentage is held until the total reaches an agreed cap, then it stops
- Reserve after closure: when an account is closed, providers often hold the balance for months to cover late disputes
Ask which type you're being offered. A cap is almost always better for you than an open-ended percentage.
How to get a better deal
Reserves are more negotiable than most people think, especially if you prepare.
1. Show your processing history.
Six to twelve months of clean statements with low disputes is your strongest argument.
2. Show your dispute and refund rates.
If you can show disputes well below 1% of transactions, you're a lower risk than the provider assumes.
3. Explain your business model clearly.
A licensed pharmacy with prescription checks and clear refund policies looks very different from an anonymous webshop. Lead with your licence.
4. Ask for a review date.
Get it written into your contract: "Reserve to be reviewed after 6 months of processing." Then put the date in your diary.
5. Ask for a cap.
"10% until €10,000 is held" is much easier to live with than "10% forever".
6. Plan your cash flow for it.
If you know you'll get a 10% reserve for 180 days, factor it into your planning from month one. It hurts most when it's a surprise.
How to get held funds released
If money is being held longer than you expected:
- Check your contract for the release schedule
- Ask in writing for a statement of how much is held and when each amount will be released
- Keep handling refunds properly. New disputes can extend the hold
- Ask for a partial release if your disputes have stayed low. Providers can agree to this, but only if you ask
This article is general information, not financial or legal advice. Reserve terms depend on your provider and contract.